Contractor Payment Schedule and Deposit Rules by State
Understand contractor payment schedule and deposit rules by state to avoid risky upfront payments. Call (833)-700-4293 for guidance on protecting your project funds.
By Julia Hayes
Learn more about Exterior Painting for guides, costs, and what to expect.
Compare Exterior Painting Pros Near You
Enter your ZIP code to compare top-rated local professionals and request free quotes.
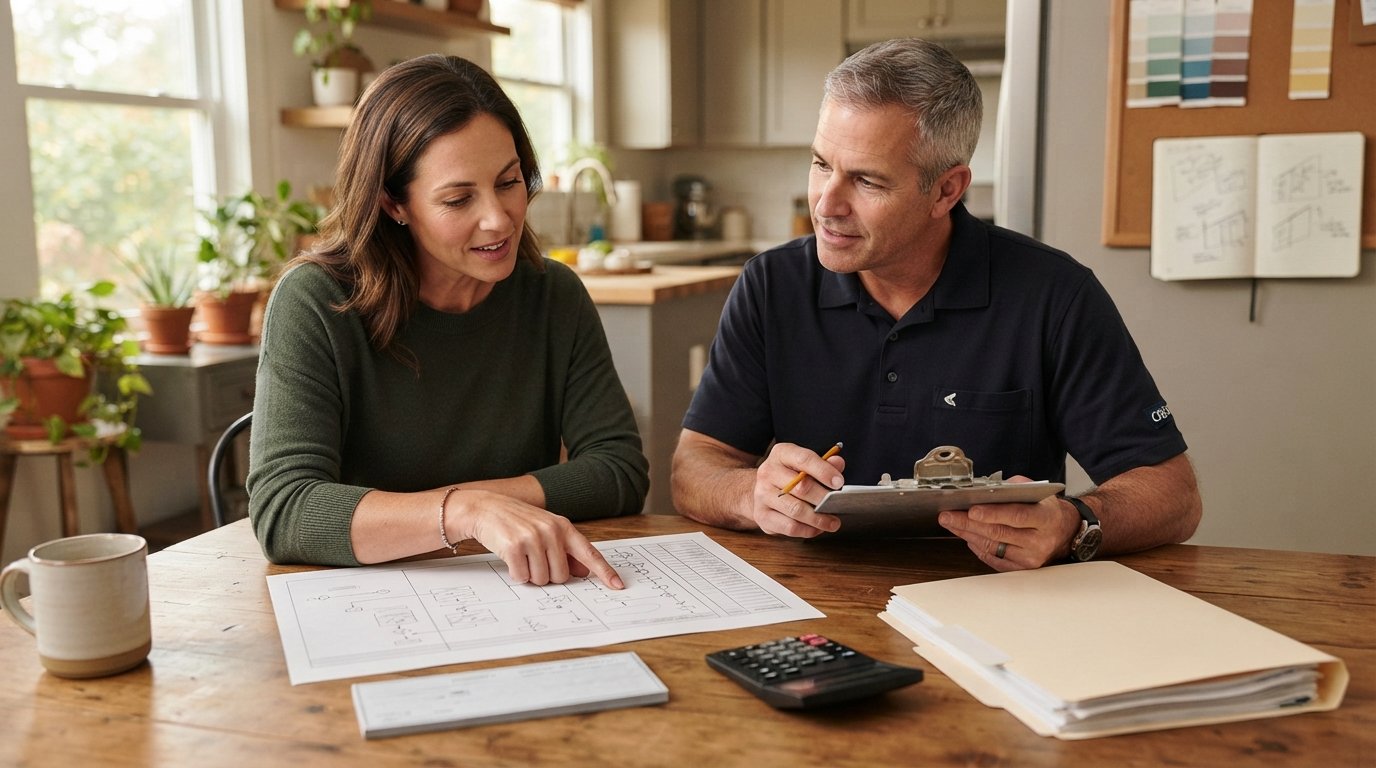
You have saved for years, picked the perfect tile, and finally signed a contract for your dream kitchen. The last thing you want is to hand over a large check before a single cabinet is hung, only to watch your contractor disappear. Yet that exact scenario plays out in thousands of disputes every year, and it almost always traces back to one root cause: a poorly structured payment schedule. Understanding the contractor payment schedule and deposit rules by state is not just legal trivia, it is the single most effective way to protect your money, your project timeline, and your sanity.
In most states, the law sets hard limits on how much a contractor can collect before work begins, and many states also mandate specific written contract terms. But the rules vary wildly: some states cap deposits at 10 percent, others allow one third, and a few have no statutory cap at all, relying instead on case law and consumer protection statutes. This guide breaks down what homeowners actually need to know: why large upfront deposits are dangerous, how milestone schedules should work for remodels, roofing, and HVAC, what lien waivers mean for your final payment, and how to choose a payment method that gives you leverage if something goes wrong. We will also show you how to use resources like Homes.Contractors to verify local professionals before you ever write a check.
Why Large Upfront Deposits Are Risky (and Often Illegal)
The core problem with a large upfront deposit is simple: once a contractor holds your money, your leverage evaporates. If the crew stops showing up, if materials are never ordered, or if the work is shoddy, you are left chasing a refund while your project sits idle. Consumer protection agencies across the country report that deposit disputes are among the most common complaints filed against home improvement contractors. In the worst cases, homeowners pay 50 percent or more upfront and never see the contractor again.
Beyond the practical risk, many states treat excessive deposits as a legal violation. Several states explicitly cap the initial deposit at 10 percent of the contract price or $1,000, whichever is less, for home improvement contracts. Others set the cap at one third of the total, and some require that deposits be held in escrow until materials are delivered. When a contractor asks for a deposit that exceeds your state's legal limit, that is a red flag that should stop the project cold. It may indicate the contractor is undercapitalized, using your money to fund a different job, or simply unfamiliar with the regulations that govern their own industry.
There is also a practical cash flow reason to avoid large deposits. A legitimate contractor typically has supplier accounts, a line of credit, and enough working capital to order materials and schedule labor without relying on your upfront cash. A contractor who demands 50 percent before ordering a single two by four is often a contractor who cannot get credit from suppliers, which is itself a warning sign about their financial stability. For a deeper look at how to vet professionals before signing anything, see the contractor directory resources at Homes.Contractors, which covers licensing and background checks by trade.
Typical Milestone Schedules for Remodels, Roofing, and HVAC
A milestone schedule ties each payment to a verifiable phase of completion, which keeps your money aligned with actual progress. The exact percentages vary by project type and region, but the underlying principle is consistent: never pay for work that has not been completed and inspected. Below are typical structures that align with consumer protection guidance and industry best practices.
Whole-Home and Kitchen Remodels
For a major remodel, a common and defensible schedule looks like this:
- Deposit (10 to 15 percent): Due at signing, used to secure the schedule and order long lead-time materials.
- Rough-in completion (25 percent): Paid after framing, electrical, plumbing, and HVAC rough-ins pass inspection.
- Drywall and finishes (25 percent): Paid after drywall is hung and finished, and cabinets or flooring are delivered.
- Substantial completion (25 percent): Paid when fixtures, trim, and paint are installed and the space is usable.
- Final payment (10 to 15 percent): Held until the punch list is complete and you have signed off.
Notice that the final payment is large enough to matter. That retainer is your leverage to get punch list items fixed promptly. A contractor who insists on 100 percent payment before the punch list is finished is asking you to give up your only remaining bargaining chip. If a contractor proposes a schedule front-loaded with 40 or 50 percent before demolition, push back and ask for a milestone-based structure instead.
Roofing and HVAC Replacements
Roofing and HVAC projects are shorter and more material-intensive, so the schedules differ. For a roof replacement, a reasonable structure is a 10 to 20 percent deposit to order shingles and schedule the crew, a progress payment when tear-off and underlayment are complete, and the balance upon final inspection and cleanup. For HVAC, many contractors ask for 30 to 50 percent to order equipment, which can be justified because the equipment is a large, specific purchase. Even so, never pay the full balance before the system is installed, tested, and running to your satisfaction. Hold back at least 10 percent until you have verified airflow, refrigerant charge, and thermostat operation.
One useful rule of thumb across all trades: no single payment should exceed the value of the work completed plus materials stored on site. If a contractor cannot document what your money is buying, that is a schedule problem you should resolve before work begins. PlanRemodel's service-specific directories can help you compare how local contractors in your area typically structure payments, since norms vary by state and even by metro area.
Lien Waivers and Why Final Payment Protects You
Mechanics lien laws allow contractors, subcontractors, and suppliers to place a lien on your property if they are not paid. This means that even if you paid your general contractor in full, a subcontractor who was stiffed can come after your home. The best defense is a combination of progress lien waivers and a final unconditional lien waiver collected at the end of the project, tied to your final payment.
A lien waiver is a document in which a contractor or supplier acknowledges receipt of payment and waives the right to file a lien for that amount. Progress waivers should be collected each time you make a payment, and they should cover all parties who worked during that phase. At final payment, insist on a final unconditional waiver from the general contractor and, ideally, from major subcontractors and suppliers. Do not release the final payment until you have those waivers in hand, along with a certificate of occupancy if one is required and a final inspection sign-off.
The final payment also protects you against incomplete punch lists and warranty issues. A common mistake is to pay the last 10 percent before the contractor has returned to fix cosmetic defects or adjust a door that sticks. Hold that money until every item on the punch list is resolved and you have written confirmation of the warranty terms. If a dispute arises, the final payment gives you the ability to negotiate rather than litigate. For homeowners in states with strong lien protections, such as California and Texas, this step is especially important because lien deadlines can be short and the paperwork requirements are strict.
State-by-State Deposit Caps and Written Contract Requirements
Deposit rules vary significantly, and the details matter. The table below summarizes the general landscape, but always verify the current statute or consult a local attorney before signing, because legislatures update these rules regularly and local ordinances may add requirements.
- California: Down payments on home improvement contracts generally cannot exceed $1,000 or 10 percent of the contract price, whichever is less. Written contracts are required for projects over $500, and the contract must include a schedule of payments.
- New York: No statutory percentage cap for most home improvement contracts, but written contracts are required for jobs over $500, and deposits must be reasonable. Local consumer protection laws may add limits.
- Texas: No statewide percentage cap, but written contracts are required for projects over $5,000, and the contract must include a payment schedule. Lien waiver rules are strict.
- Florida: No explicit deposit cap, but the contractor must provide a written contract for projects over $2,500 that includes a payment schedule and a notice of the homeowner's right to cancel.
- Illinois: Written contracts are required for projects over $1,000, and the contract must include a payment schedule. Deposit limits are governed by the Home Repair and Remodeling Act.
- Pennsylvania: The Home Improvement Consumer Protection Act requires written contracts over $500 and limits deposits to one third of the contract price before work begins, with additional limits on progress payments.
- Washington: Written contracts are required for projects over $500, and deposits are limited to 10 percent of the contract price or $1,000, whichever is less, for residential remodels.
- Massachusetts: Written contracts are required for projects over $1,000, and deposits are limited to one third of the contract price, with the balance due upon completion.
These examples illustrate the range: from strict 10 percent caps to states with no percentage limit but robust written contract requirements. The practical takeaway is to ask two questions before signing: what is the maximum deposit your state allows for this type of project, and what written terms must the contract include? A reputable contractor will know the answers and will not hesitate to put the payment schedule in writing. If a contractor resists a written schedule or asks for cash with no receipt, walk away. PlanRemodel's localized directories can help you find contractors who are familiar with your state's specific requirements.
Credit Card Versus Cash: Choosing a Payment Method That Protects You
The method you use to pay matters almost as much as the schedule itself. Cash offers no paper trail and no recourse if the work goes wrong. Checks are better because they create a record, but they still offer limited protection once deposited. Credit cards, by contrast, give you the right to dispute charges for services not rendered or goods not delivered, which is a powerful tool if a contractor fails to perform.
Whenever possible, pay deposits and progress payments with a credit card, even if you plan to pay the balance off immediately. The card issuer's dispute process can help you recover funds if a contractor abandons the job or delivers substandard work that they refuse to fix. Debit cards offer weaker protections, and wire transfers and cash apps are essentially irreversible. If a contractor offers a discount for cash, weigh that savings against the risk: a 5 percent discount is small comfort if you lose a 20 percent deposit to a vanished contractor.
For large projects, consider paying by credit card up to the card's limit and using a check or electronic transfer for the remainder, always with a written receipt and a lien waiver. Keep a dedicated folder with the signed contract, the payment schedule, all receipts, change orders, and lien waivers. If a dispute escalates, that folder is your evidence. Many consumer protection agencies and state licensing boards will ask for it when you file a complaint.
Putting It All Together: A Practical Checklist for Homeowners
Before you sign a contract, run through this sequence to make sure your payment schedule and deposit align with state rules and protect your interests:
- Verify the contractor's license and insurance through your state licensing board and cross-check reviews on a directory such as Homes.Contractors.
- Confirm your state's deposit cap and written contract requirements, and ask the contractor to cite the relevant statute in the contract.
- Negotiate a milestone-based schedule with a final payment of at least 10 percent held until punch list completion and lien waivers are delivered.
- Pay with a credit card when possible, and collect a signed lien waiver with every payment.
- Keep a complete paper trail and do not release final payment until you have inspected the work and received all warranty documents.
A well-structured payment schedule is not a sign of distrust, it is a sign of professionalism on both sides. Contractors who understand their state's rules and are confident in their work will welcome a milestone-based agreement because it protects them too, ensuring they are paid for completed phases without overextending credit. PlanRemodel's referral platform connects homeowners with pre-vetted contractors who expect to work within these frameworks, and it lets you request multiple quotes so you can compare not just price but also proposed payment terms. When you are ready to start your project, use the resources at PlanRemodel to find professionals in your state and to review the ratings-by-state feature before you commit.