How to Finance a Home Improvement Project With Bad Credit
Need to finance a home improvement project with bad credit? Get free estimates and compare loan options. Call (833)-700-4293 for expert guidance.
By Benjamin Adler
Learn more about Exterior Painting for guides, costs, and what to expect.
Compare Exterior Painting Pros Near You
Enter your ZIP code to compare top-rated local professionals and request free quotes.
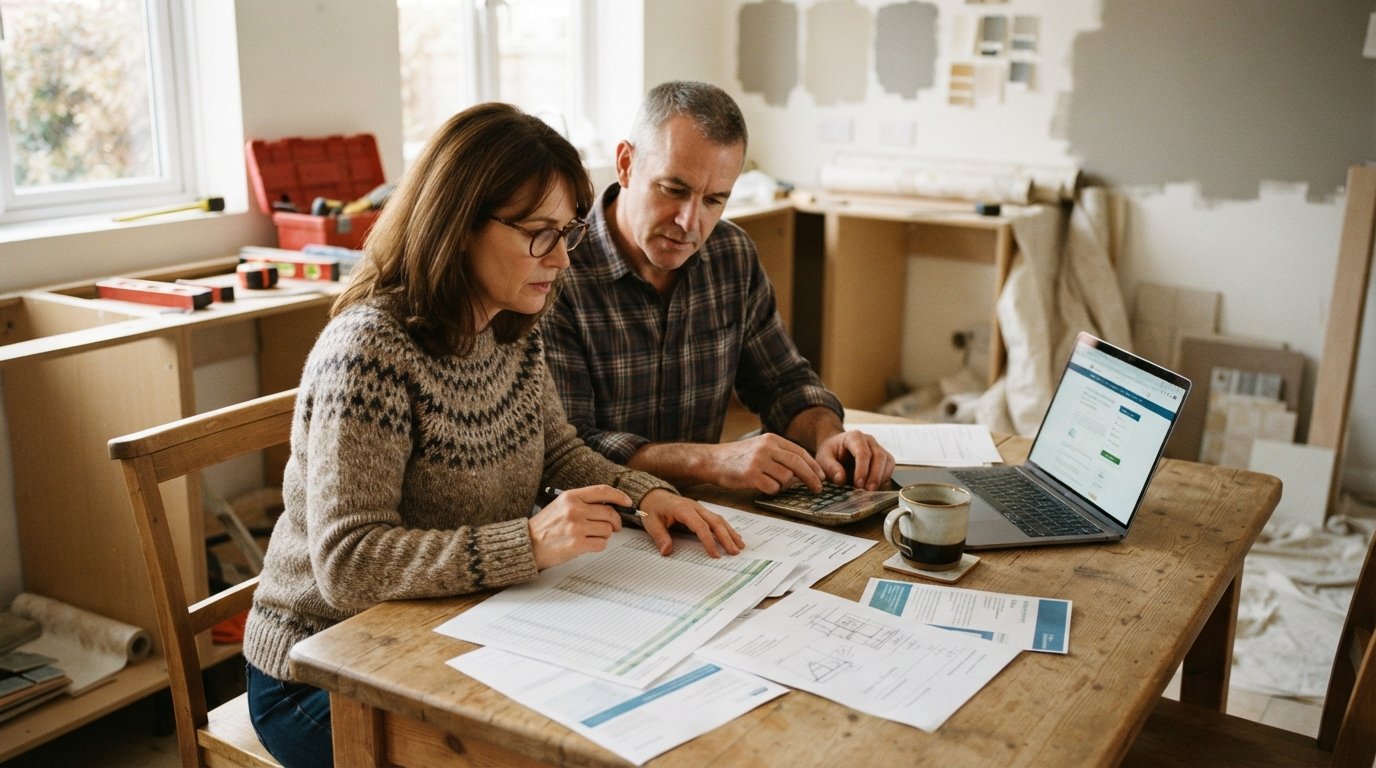
Your roof is leaking, your kitchen is stuck in 1995, or your bathroom has a leak that keeps getting worse. You know the project cannot wait, but your credit score is not what you want it to be. Maybe you have missed payments in the past, or you are carrying too much debt, or you simply have not had the chance to build a strong credit history yet. Whatever the reason, the thought of applying for a loan and getting rejected is stressful.
Here is the good news: bad credit does not close every door. There are still real ways to finance a home improvement project, and some of them do not even require a traditional bank loan. You just need to know where to look and how to present yourself as a strong candidate. This guide walks you through how to finance a home improvement project with bad credit, from comparing loan types to avoiding predatory traps that target homeowners in tough spots.
Before you sign anything, remember that the number you are financing matters as much as the loan itself. If you finance too much, you pay interest on money you did not need. If you finance too little, you may run out of cash mid-project. That is why the first step is always the same: get accurate estimates before you start shopping for money. A resource like Homes.Contractors can help you find pre-vetted local pros who provide detailed quotes, so you know the real number before you borrow.
Start With Estimates, Not Loans
It is tempting to apply for a loan first and figure out the project later. That approach often backfires. If you borrow $30,000 for a kitchen remodel but the actual bids come in at $18,000, you are stuck paying interest on $12,000 you did not need. Worse, if you borrow too little and the project stalls halfway through, you may end up with a torn-up kitchen and no money to finish it.
Get at least three written estimates from licensed contractors. The estimates should break down materials, labor, permits, and timelines. Ask each contractor what could cause the price to go up and what is not included. This helps you build a realistic budget with a contingency fund of 10 to 20 percent for surprises.
Once you have a solid number, you can shop for financing with confidence. You will know exactly how much you need, which makes it easier to compare loan offers and avoid borrowing more than necessary.
Compare Your Financing Options
When you have bad credit, not all loans are created equal. Some are designed for homeowners with imperfect credit, while others are almost impossible to get without a strong score. Here are the main options to consider, along with what each one requires and how it treats borrowers with credit challenges.
Personal Loans
Personal loans are unsecured, meaning you do not put your home on the line. That makes them safer than home equity loans if you are worried about losing your house. However, because they are unsecured, lenders take on more risk and charge higher interest rates, especially for borrowers with bad credit.
Online lenders and credit unions are often more flexible than big banks. Some specialize in borrowers with scores below 600. You will pay a higher APR, but you can still get funded. Watch out for origination fees, prepayment penalties, and short repayment terms that make monthly payments unaffordable.
Home Equity Loans and HELOCs
If you have owned your home for a while, you may have equity you can tap. A home equity loan gives you a lump sum with a fixed rate. A home equity line of credit (HELOC) works like a credit card, letting you draw funds as needed.
These options usually have lower interest rates than personal loans because they are secured by your home. But that is also the risk: if you cannot repay, you could lose your home. Bad credit makes approval harder, but some lenders will work with scores in the 600s if you have significant equity. Credit unions are often more willing to negotiate than national banks.
Contractor Financing
Some contractors offer financing through third-party lenders. This can be convenient, especially if the contractor has a relationship with a lender that specializes in home improvement loans. However, you need to read the fine print carefully. Some contractor financing deals come with deferred interest, meaning if you do not pay the full balance before the promotional period ends, you owe interest retroactively from day one.
Other contractor financing offers may have high APRs or hidden fees. Always ask for the full terms in writing and compare them to what you could get on your own. If a contractor pressures you to finance through their partner without letting you shop around, that is a red flag. For more warning signs, see our guide on red flags of a bad home improvement contractor.
Credit Union and FHA Title I Loans
Credit unions are member-owned and often more forgiving of imperfect credit than banks. If you have a relationship with a credit union, start there. They may offer personal loans, home equity products, or even special home improvement loans with more flexible underwriting.
The FHA Title I Property Improvement Loan program is another option. It is insured by the Federal Housing Administration and designed for homeowners who cannot get traditional financing. You can borrow up to $25,000 for a single-family home, and the loan can be used for repairs, improvements, or even accessibility upgrades. Bad credit does not automatically disqualify you, though lenders will still check your ability to repay. Not all lenders participate, so you may need to call around.
Strategies to Improve Your Approval Odds
Even if your credit is not great, you can take steps to make yourself a more attractive borrower. These strategies can help you get approved, get a lower rate, or both.
- Add a co-signer: A co-signer with good credit agrees to repay the loan if you do not. This reduces the lender's risk and can help you qualify for better terms. Just be sure the co-signer understands the responsibility.
- Use a secured credit card for small projects: If your project is small, like a minor repair, a secured credit card can work. You put down a deposit, which becomes your credit limit. On-time payments build your credit history.
- Make a larger down payment: If you can put more money down, you borrow less. Lenders see less risk and may approve you even with a lower score.
- Pay down existing debt: Reducing your debt-to-income ratio can improve your approval chances. Even paying off a small credit card can help.
- Ask about manual underwriting: Some credit unions and community banks will manually review your application, looking at your full financial picture instead of just a score.
These steps take time, but even a few weeks of focused effort can make a difference. If you are not in a rush, use the time to improve your profile before you apply.
Avoid Predatory Financing
When you have bad credit, you are a target for predatory lenders. These companies know you are desperate and may offer terms that trap you in a cycle of debt. Watch out for:
- Interest rates above 36 percent APR
- Fees that are not clearly disclosed upfront
- Pressure to sign immediately without time to review
- Balloon payments that require a large lump sum at the end
- Loans that require you to sign over the title to your home or car
If an offer sounds too good to be true, it probably is. Take your time, read every document, and ask questions. A legitimate lender will never rush you or make you feel bad about your credit. They will explain the terms clearly and give you time to decide.
Also be wary of contractors who push you toward a specific lender without letting you compare options. That is one of the red flags mentioned earlier. You have the right to shop around.
Work With a Vetted Contractor
Financing is only half the battle. You also need someone qualified to do the work. Hiring the wrong contractor can turn a manageable project into a financial disaster, especially if you are already stretching to pay for it.
Look for contractors who are licensed, insured, and have a track record in your area. Ask for references and check them. Get everything in writing, including the scope of work, payment schedule, and timeline. Never pay the full amount upfront. A reasonable deposit is usually 10 to 30 percent.
If you are not sure where to start, a directory like Homes.Contractors can connect you with pre-vetted local pros in roofing, HVAC, plumbing, flooring, and more. You can request multiple quotes and compare them side by side, which helps you avoid overpaying and gives you leverage when negotiating.
Putting It All Together
Financing a home improvement project with bad credit is not easy, but it is possible. Start by getting accurate estimates so you know exactly how much you need. Then compare your options: personal loans, home equity products, contractor financing, credit unions, and FHA Title I loans. Improve your approval odds with a co-signer, a larger down payment, or by paying down debt. Avoid predatory lenders and contractors who pressure you into bad deals.
Most importantly, take your time. A rushed decision can cost you thousands. A thoughtful one can get your project done without wrecking your finances.
For personalized assistance and to explore your options, call (833)-700-4293 or visit PlanRemodel.com to connect with trusted professionals in your area.