How to Work with a Contractor on an Insurance Claim Repair
Coordinate contractor and insurer smoothly on an insurance claim repair. Call (833)-700-4293 to connect with pre-vetted pros and avoid surprise bills.
By Julia Hayes
Learn more about General Contracting for guides, costs, and what to expect.
Compare General Contracting Pros Near You
Enter your ZIP code to compare top-rated local professionals and request free quotes.
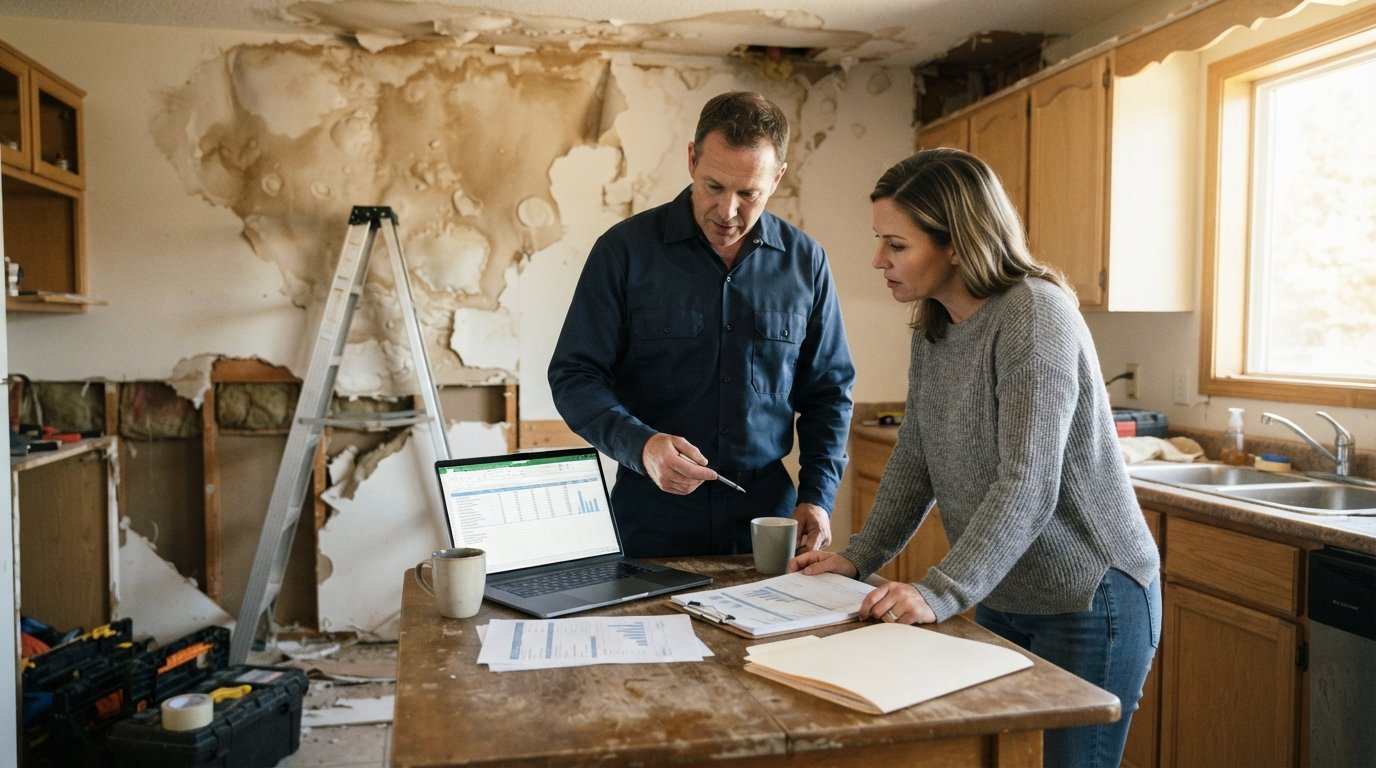
When a storm, fire, or burst pipe forces you to file an insurance claim, the repair process can feel like a second job. You are suddenly balancing an adjuster's schedule, a contractor's estimate, and a policy document full of unfamiliar terms. The stakes are high: a single misstep can leave you paying thousands out of pocket for damage your policy was supposed to cover. The key to a smooth outcome is understanding how to work with a contractor on an insurance claim repair, because the contractor and the insurer must speak the same language for your claim to be approved and funded correctly.
This guide walks you through the entire coordination process, from the first inspection to the final settlement. You will learn why the scope of loss and the contractor's estimate rarely match, who is responsible for supplemental claims when hidden damage appears, and how to avoid the costly mistake of settling your claim before the work is done. By the end, you will have a practical framework for managing the contractor-insurer relationship so your repair is completed fully and fairly.
Understand the Two Estimates: Scope of Loss vs. Contractor Estimate
The first source of confusion in any insurance repair is the difference between the insurer's scope of loss and the contractor's estimate. The scope of loss is a document prepared by the insurance adjuster that outlines the covered damage and the estimated cost to repair it, based on the adjuster's inspection and the insurer's pricing software. The contractor's estimate is a detailed, line-by-line proposal from the contractor who will actually perform the work. These two documents are rarely identical, and that is normal.
The adjuster's scope is built on a visual inspection, often completed quickly and without opening walls or removing materials. It may miss hidden damage, use regional pricing that is lower than your local market, or exclude items the adjuster considers cosmetic. The contractor's estimate, by contrast, reflects the actual labor and materials required in your specific home, including the cost of permits, disposal fees, and code upgrades that the insurer may not have anticipated. When you review both documents side by side, you can identify gaps before work begins.
A useful practice is to ask your contractor to produce an estimate that mirrors the line items in the adjuster's scope. This allows for an apples-to-apples comparison. If the contractor's price is higher, they should be able to explain why, for example, the insurer's scope assumes a standard shingle while your home requires a specific architectural grade to match the existing roof. These explanations become the basis for a supplemental claim or a negotiated revision. For a deeper look at the repair-versus-replace decision that often arises during this stage, see this guide on roof repair or replace decision rule, which explains how to weigh costs when the insurer's scope covers only a patch.
Never assume the adjuster's scope is final. It is a starting point, and insurers expect contractors to submit revised estimates when the initial scope is incomplete. Your contractor should be comfortable communicating directly with the adjuster to clarify line items, and you should be copied on all correspondence. This transparency prevents surprises and builds a documented record of why costs changed.
Who Handles Supplemental Claims When Hidden Damage Appears
Hidden damage is the wild card in every insurance repair. Once the contractor opens a wall or removes flooring, they may find rotted framing, mold, or damaged wiring that the adjuster could not see. At that moment, a critical question arises: who is responsible for filing the supplemental claim? The answer is that you, the homeowner, are ultimately responsible for the claim, but your contractor plays a central role in documenting the damage and justifying the additional cost.
Most insurance policies require prompt notice of additional damage. If your contractor discovers hidden issues, they should stop work in that area, photograph the damage, and provide a written supplement request that includes the cause, the required repair, and the cost. You then submit this documentation to your adjuster. Some contractors will communicate directly with the adjuster on your behalf, but the claim itself remains yours. Clarify this division of responsibility before work begins so there is no confusion when a surprise appears.
Supplemental claims are common and insurers expect them. The key is timing and documentation. A supplemental claim filed weeks after the damage is discovered, without photos or a clear explanation, is far more likely to be denied. A claim filed within days, with a detailed contractor report and photos, is typically processed smoothly. Your contractor should be able to provide a supplement template or at least a written narrative that ties the hidden damage to the original claim event. If they hesitate, that is a red flag about their experience with insurance work.
Keep a shared folder or cloud drive where both you and the contractor store photos, estimates, and correspondence. This simple habit ensures that when the adjuster asks for evidence, you can provide it immediately. It also protects you if the insurer disputes the cause of the hidden damage. Remember that the burden of proof is on you, and your contractor's documentation is your strongest evidence.
Getting Contractor Documentation the Insurer Will Accept
Insurance adjusters process thousands of claims, and they have clear standards for what documentation they will accept. A handwritten note or a verbal estimate will not move a claim forward. To get paid, your contractor must provide documentation that is detailed, itemized, and consistent with industry standards. Understanding these requirements helps you guide your contractor and avoid back-and-forth delays.
At a minimum, the insurer will expect a written estimate on the contractor's letterhead that includes the following elements:
- Line-item breakdown of labor and materials, with quantities and unit prices
- Description of the damage and the proposed repair method
- Photos of the damage before and during the repair
- Proof of the contractor's license and insurance
- Any applicable permits and code upgrade requirements
Beyond these basics, the most persuasive documentation includes a narrative that connects the damage to the covered event. For example, instead of listing "replace drywall," the estimate should state "remove and replace water-damaged drywall in the north wall of the living room, caused by roof leak on [date]." This specificity leaves no room for the adjuster to question whether the damage is covered. Your contractor should also use the same terminology as the adjuster's scope, such as "tear-out," "drywall," and "paint," so the two documents can be compared directly.
If your contractor uses estimating software like Xactimate, which is common in the insurance industry, ask for a copy of the estimate in that format. Many insurers prefer Xactimate because it uses the same pricing database as their adjusters, which reduces disputes. If your contractor does not use Xactimate, they can still provide a detailed estimate in a spreadsheet or PDF, but they should be prepared to justify any line items that differ from the insurer's pricing. A contractor who has worked on insurance claims before will already know this and will provide documentation without being asked.
Avoid Settling Your Claim Before Repairs Are Complete
One of the most costly mistakes homeowners make is accepting a final settlement before the repair work is finished. The insurer may offer a lump sum based on the initial scope of loss, and it can be tempting to take the check and move on. But once you cash that check or sign a release, you may lose the ability to claim additional funds for hidden damage or underestimated costs. The general rule is simple: do not sign a final settlement or release until the work is complete and you are satisfied with the result.
Insurance policies typically require you to complete repairs within a certain timeframe, but that does not mean you must accept the first offer. If your contractor discovers additional damage after the initial settlement, you can still file a supplemental claim, but it is much harder if you have already signed a release. To protect yourself, ask the adjuster to hold back a portion of the settlement (often called a recoverable depreciation holdback) until the work is done and inspected. This is standard practice in many policies and gives you leverage to ensure the contractor completes the job correctly.
Another risk is settling for actual cash value (ACV) when you are entitled to replacement cost value (RCV). ACV pays you the depreciated value of your damaged items, while RCV pays the full cost to replace them. If your policy includes RCV coverage, you can typically claim the difference after the work is complete. Your contractor's final invoice and photos of the completed work are the evidence you need to recover that depreciation. Do not let the insurer close the claim until you have submitted these documents and received the final payment.
Communication is your best defense. Keep your adjuster informed of the repair timeline, and ask for written confirmation of what is required to release the final payment. If the insurer pressures you to settle early, explain that you are waiting for the contractor to complete the work and provide final documentation. A reputable insurer will respect that position.
Choosing a Contractor Experienced with Insurance-Funded Projects
Not every contractor understands the insurance claim process. A contractor who is skilled at remodeling but unfamiliar with adjusters, scopes of loss, and supplemental claims can inadvertently cost you money. When you are hiring for an insurance repair, experience with insurance-funded projects should be a top criterion, alongside licensing, insurance, and references.
Ask potential contractors directly about their experience with insurance claims. Good questions include: How many insurance claims have you worked on in the past year? Can you provide a sample supplement request? How do you communicate with adjusters? Will you handle the documentation, or will I need to? A contractor who has a system for insurance work will answer these questions confidently and can explain the process clearly. They should also be willing to wait for the insurer's approval before starting work, which is a sign that they understand the financial flow of a claim.
It also helps to work with a contractor who is familiar with your insurer's preferred documentation format. Some insurers have specific requirements for photos, estimates, and invoices. A contractor who has worked with your insurer before will know these requirements and can avoid delays. If you are unsure where to start, a directory of pre-vetted contractors can simplify the search. For example, Homes.Contractors offers a comprehensive online directory and informational resource for homeowners in the United States seeking qualified, pre-vetted contractors for home improvement and repair services, including those experienced with insurance claims. Using a directory like this can help you compare multiple contractors and find one who understands the claim process.
Finally, trust your instincts. A contractor who dismisses your questions about insurance, pressures you to sign a contract before the insurer approves the scope, or asks you to pay the full cost upfront and "work it out with the insurer later" is a risk. The right contractor will be patient, transparent, and willing to collaborate with your adjuster. They will also provide a written contract that clearly states the scope of work, payment schedule, and contingency for supplemental claims. Review that contract carefully, and do not sign until you understand how additional work will be handled.
Practical Steps for Coordinating Contractor and Insurer
Managing an insurance repair is a project in itself. To keep the process on track, follow a structured approach that keeps all parties aligned. The following steps outline a proven sequence that homeowners can use from the first inspection to the final payment.
- Document the damage immediately. Take photos and videos before any repairs begin, and keep a detailed inventory of damaged items. This record supports both the initial claim and any supplements.
- Get the adjuster's scope of loss in writing. Ask for a copy and review it with your contractor. Identify any missing line items or discrepancies.
- Have your contractor prepare a detailed estimate. Ensure it is line-itemed, includes photos, and uses industry-standard terminology. Submit it to the adjuster for review.
- Establish a communication protocol. Decide who will talk to the adjuster (you, the contractor, or both) and how often. Confirm everything in writing, preferably by email.
- Handle supplements promptly. If hidden damage appears, have the contractor document it and submit a supplement request within days, not weeks.
- Do not settle until the work is complete. Wait for final inspection and a certificate of completion before accepting the final payment or signing a release.
Following these steps reduces the chance of miscommunication and ensures that the contractor and insurer are working from the same information. It also creates a clear paper trail if a dispute arises. Remember that you are the central coordinator in this process; neither the contractor nor the adjuster will manage the entire claim for you. Your active involvement is what keeps the repair moving forward.
In the end, a successful insurance claim repair comes down to preparation and communication. By understanding the difference between the scope of loss and the contractor's estimate, knowing who handles supplements, demanding proper documentation, and refusing to settle early, you protect your financial interests and ensure your home is restored correctly. Take the time to choose a contractor who has navigated insurance claims before, and keep the lines of communication open with your adjuster. With the right approach, you can turn a stressful claim into a completed repair that meets both your insurer's standards and your own.